|
Signature Sponsor
October 6, 2026 - Below are the highlights of EIA's most recent Short-Term Energy Outlook:
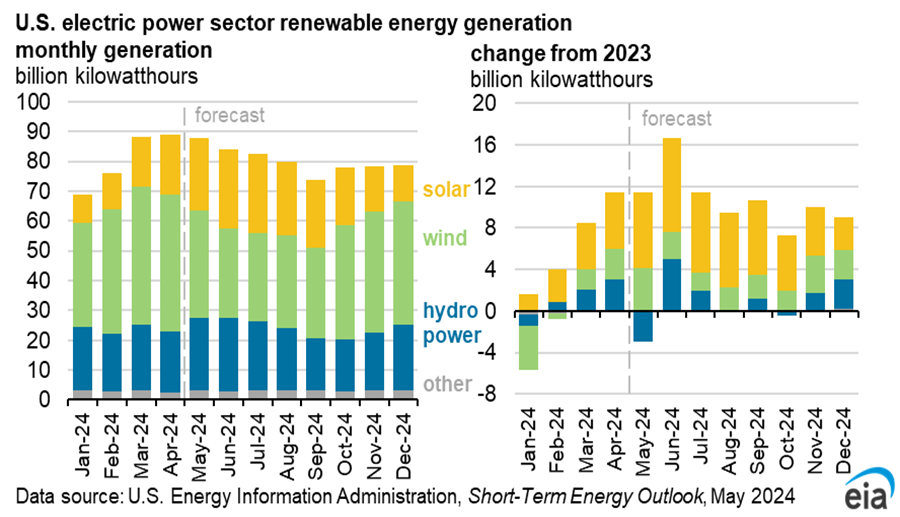
We anticipate wholesale electricity prices in 2026 to average $52 per megawatthour (MWh) across the 11 hubs we track, which is 11% higher than in 2025. Prices in 2027 are expected to decline slightly to $49/MWh on average. Some regions experienced higher wholesale electricity prices this year mainly due to weather events, such as winter storm Fern and high summer temperatures particularly in July, which affected most of the country, spiking prices compared with last year.
Wholesale electricity prices are just one component of residential electricity prices, and they are strongly influenced by natural gas prices and weather conditions. Residential electricity prices include other expenses such as transmission and distribution upgrades, capacity market auction prices in some regions, among other expenses.
We forecast wholesale prices in the PJM region this year will increase by 41% compared with 2025, the largest increase across all regions. The Northwest Mid-Columbia region saw the largest decline with prices falling 23% from 2025 levels. However, prices across most hubs in the country remain similar to 2025.
The three regions with the highest wholesale prices this year—PJM, ISO-NE, and NYISO—are expected to see declines in 2027 ranging from 7% at PJM and 14% at NYISO. Prices in those regions decline as our forecast assumes winter temperatures will return to near average this year after relatively cold weather last winter. CAISO’s prices in our forecast increase by 19% to $30/MWh in 2027 after reaching historic lows this year.
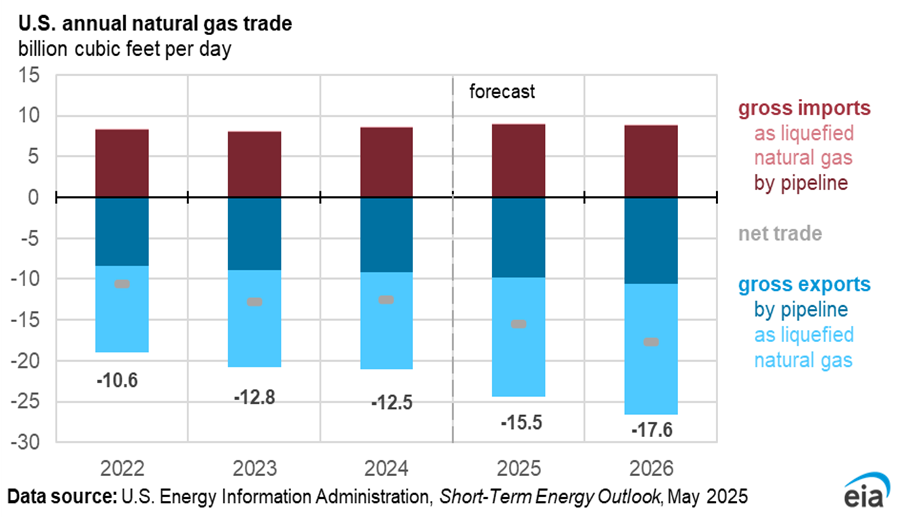  A hot summer led to an increase in electricity consumption for cooling needs in the third quarter of 2026 (3Q26), particularly from the residential and commercial sectors. Overall, electricity consumption in 3Q26 increased by 4% across the country compared with the same quarter last year. The largest increases came from the residential (6%) and commercial (5%) sectors.
We forecast electricity demand from the commercial sector, which includes data centers, to increase steadily throughout 2027, growing by 2.8% year-over-year. Demand from the industrial sector is expected to increase by 2.7%. Consumption from the residential sector is expected to remain mostly unchanged from 2026 levels.
Coal Markets
During the fall and spring, stocks of coal held by coal-fired electric power plants tend to increase as seasonal demand for the fuel for electricity generation falls relative to coal supply.
Amidst this year’s hot summer, the U.S. electric power sector drew down coal stocks to meet high electricity demand, with stocks at an estimated 100 million short tons (MMst) at the end of September compared with 105 MMst in September 2025.
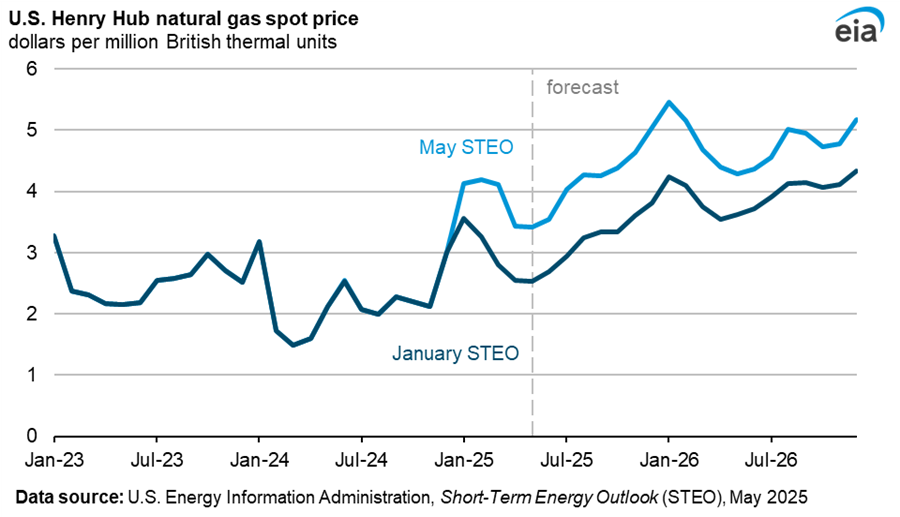 During the upcoming winter months (November–March), we expect U.S. coal stocks to remain relatively steady, averaging 106 MMst before a late-winter rise in March 2027. Coal stocks fell between November and February during the past two winters in response to colder-than-normal weather and associated increase in power generation. However, milder expected weather this winter, upcoming planned coal plant retirements, and low natural gas prices should keep coal generation this winter lower than last winter.
|
|