|
Signature Sponsor
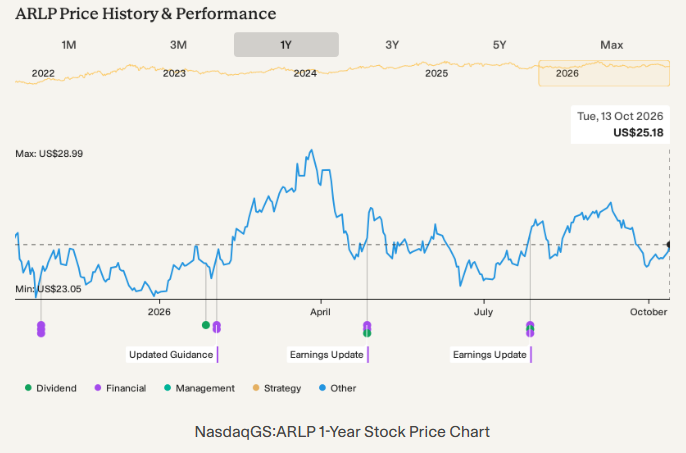
October 14, 2026 - Alliance Resource Partners is preparing to release its third quarter 2026 results after a period in which value metrics such as Forward P/E and P/CF have screened below sector averages, reinforcing attention on how the coal and royalty portfolio is performing.
The partnership is leaning into energy related technologies and infrastructure alongside its coal and mineral interests, which places more focus on how efficiently it can convert contracted volumes and royalty production into consistent cash generation.
We will now examine how Alliance Resource Partners' investment narrative could be shaped by its value metrics screening below industry averages.
Alliance Resource Partners Investment Narrative Recap
To own Alliance Resource Partners, you need to be comfortable with a coal heavy operation that is trying to squeeze more cash from lower cost mining and a growing oil and gas royalty platform. The short term hinge is whether mine efficiency and nearly fully committed 2026 and 2027 coal volumes offset normalized pricing and keep cash generation resilient.
The biggest risk right now sits in weaker coal economics and asset specific issues. Lower average realized prices, contract mix tilting to index linked volumes and the prior impairment at Mettiki show how quickly mine level returns can change. Volatile Bitcoin holdings also add noise to reported earnings.
The upcoming third quarter 2026 release on 26 October is the key near term checkpoint. Management plans to review results and outlook on a same day call. This will offer a fresh look at how well Alliance Resource Partners is translating coal volume commitments and royalty investments into actual cash flow.
This update matters for the catalyst investors often focus on most: consistent free cash generation from a lower cost coal base and expanding royalties while keeping leverage contained. Any commentary on coal pricing trends, further mine changes or the contribution from recently scaled oil and gas interests will be important for judging that path.
Alliance Resource Partners' current analyst narrative points to revenues of US$2.4b and earnings of US$401.5 million by 2029. That profile assumes revenue growth of 3.7% per year, with earnings increasing by about US$137.8 million from current earnings of US$263.7 million.
|
|