|
Signature Sponsor
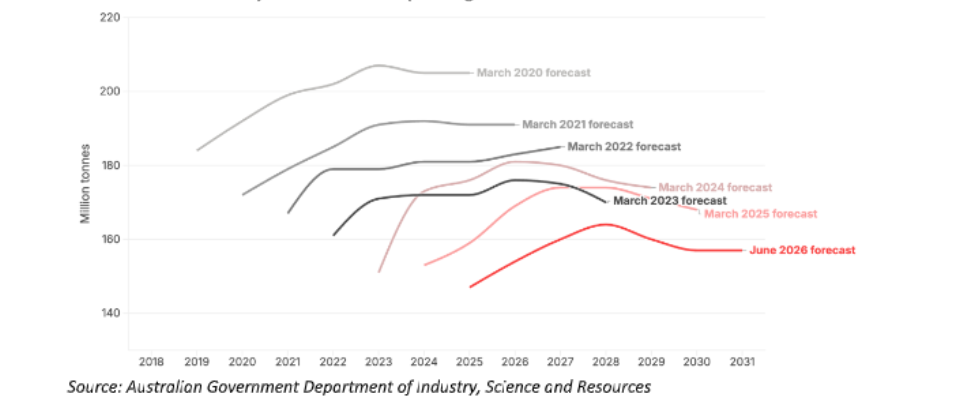
October 27, 2026 - India’s new draft National Steel Policy: Vision 2047, released by the central government in October this year, includes several positive proposals. However, it also raises important questions about where the country will source its metallurgical (met) coal from as steel production continues to rise. Decarbonization is named as one of the key pillars of the policy, which includes proposals for the development of a domestic scrap steel ecosystem, improved energy efficiency, and increased steel production for electric arc furnaces (EAFs). These would certainly be positive developments. However, the draft policy notes that the share of steel produced via the blast furnace-basic oxygen furnace (BF-BOF) technology route will increase from the current 42 percent to over 50 percent by 2047. This, along with the substantial increase in overall steel production over this time period, will increase reliance on met coal. The draft policy also highlights that the requirement for coking coal will increase from 72 million tonnes (Mt) in 2025 to 236Mt by 2047. The demand for the other type of met coal, pulverised coal injection (PCI), will rise from 17Mt to 48Mt, taking the total met coal requirement to 284Mt in 2047. The vast majority of India’s met coal requirement is imported. The draft policy notes that 92 percent of its coking coal comes from overseas and that PCI coal demand is “largely met through imports from Russia and Australia”. Global supply falling shortIndia’s forecast met coal demand of 284Mt needs to be put into the global context. According to the latest government forecasts from Australia, the world’s largest met coal exporter, total world trade in met coal was 340Mt in 2025. However, this figure includes 61Mt exported from Mongolia to China, which is likely to remain unavailable to India. In September, Steel Authority of India Limited (SAIL) imported one tonne of Mongolian met coal by air to test the country’s potential as a new supply source. However, larger volumes would have to be transported by rail from the landlocked nation to ports in Russia before being shipped to India. This is a major logistical hurdle that is unlikely to ever become financially viable. In 2025, JSW Steel had put its plans to import Mongolian met coal on hold citing these very logistical difficulties. Excluding Mongolia’s exports, global met coal trade totalled 279Mt in 2025, less than the amount the draft policy forecasts India’s steel industry will need by 2047. Australia’s met coal export forecasts keep falling
Why India needs non-coal routes for steelmakingUncertain long-term met coal supply is a significant energy security concern for India. Where supply does not meet demand, there will be cost implications. Met coal prices have been high recently, as supply has struggled to meet demand following a major mining accident in China and the subsequent temporary closure of mines for safety checks. |
|