|
Signature Sponsor
November 1, 2026 - Based on investment analysis by Melissa Tucker, published October 31, 2026. Financial figures refer to second-quarter results unless otherwise noted. Core Natural Resources’ coal operations, export infrastructure and insurance settlement could support increased shareholder returns, according to investment analyst Melissa Tucker. Tucker estimates the company’s fair value at approximately $100 per share, based on projected cash generation and share repurchases. That figure represents her valuation opinion rather than a company forecast.
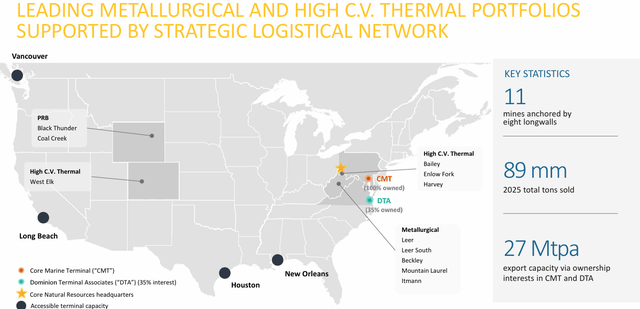
Core operates eleven U.S. mines and holds interests in two marine export terminals. Its business includes high-calorific-value thermal coal, metallurgical coal and Powder River Basin coal.
The company describes its operations as positioned in the lowest-cost quartile among U.S. metallurgical and seaborne thermal coal suppliers. Its export infrastructure provides access to international customers and flexibility in serving different markets.
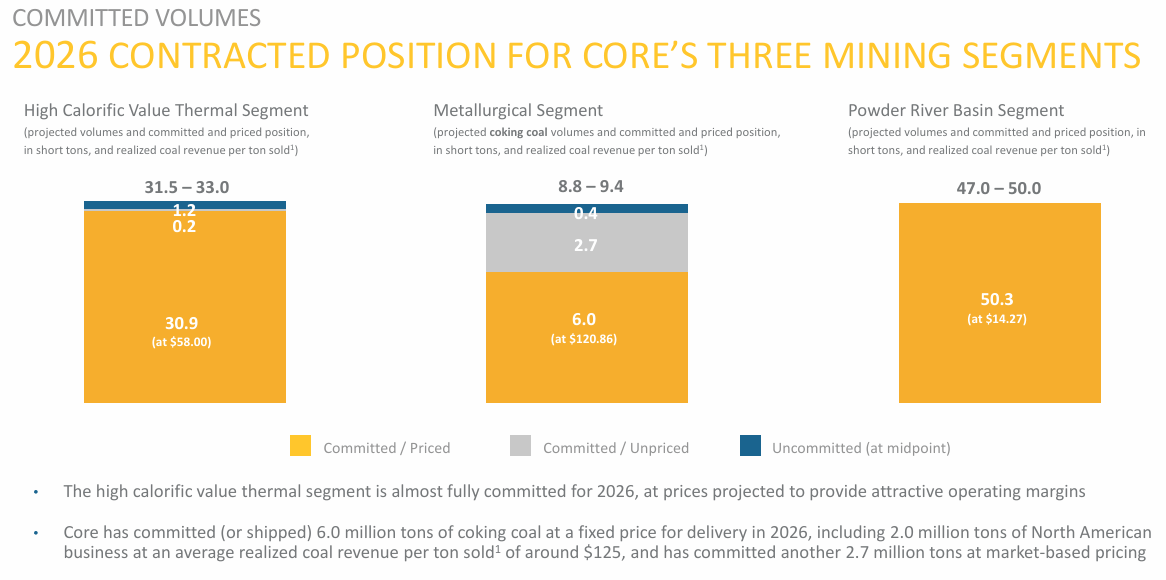
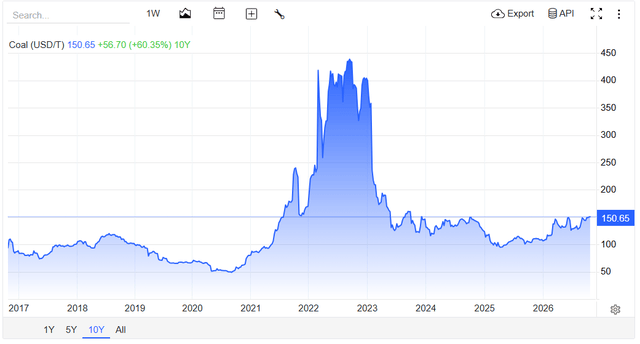
Elevated coal prices have strengthened the industry’s operating environment, although much of Core’s 2026 production was already committed at fixed prices. The benefit of stronger markets therefore depends partly on the timing and terms of future contracts.
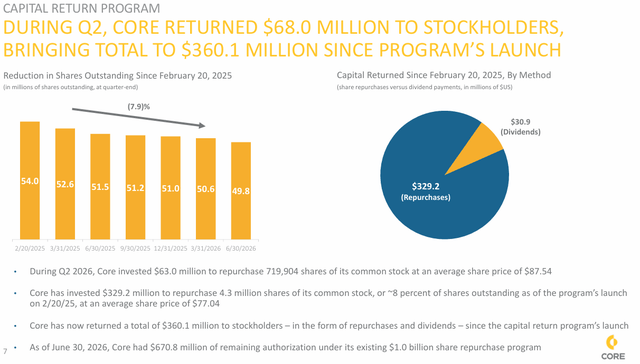
During its second-quarter conference call, management said more than half of the high-calorific-value thermal segment’s 2027 volumes were contracted. Core had secured additional business for West Elk coal linked to European pricing and Pennsylvania Mining Complex coal sold into India. Management indicated expected average realizations for the segment in the upper-$50 to low-$60-per-ton range, reflecting its mix of products and contracts. Insurance Settlement Strengthens Capital-Return Capacity Core settled its Leer South insurance claim and recognized the remaining $125.4 million in proceeds during the second quarter. Tucker views the settlement as a potential catalyst for increased repurchases during the second half of 2026. The company’s capital-return policy targets distributions equal to 75% of free cash flow through a fixed quarterly dividend of $0.10 per share and additional share repurchases.
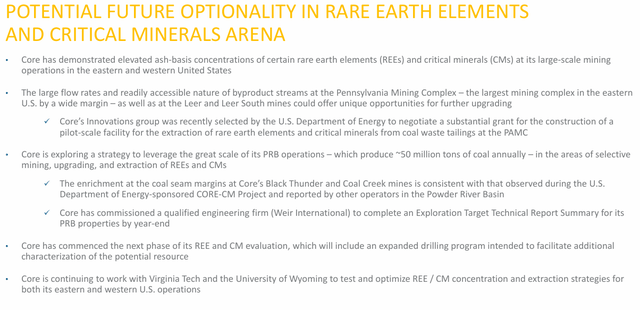
Since launching the program in February 2025, Core had invested $329.2 million in repurchases, retiring approximately 8% of its outstanding shares. Tucker expects additional cash generation and insurance proceeds to support further purchases. Critical-Minerals Development Offers Longer-Term Potential Core’s Innovations business is exploring additional uses for coal and coal-derived materials. The original analysis describes approximately $20 million in revenue, primarily associated with defense applications. The business has also been selected for Department of Energy support for a pilot-scale facility intended to recover rare-earth elements and critical minerals.
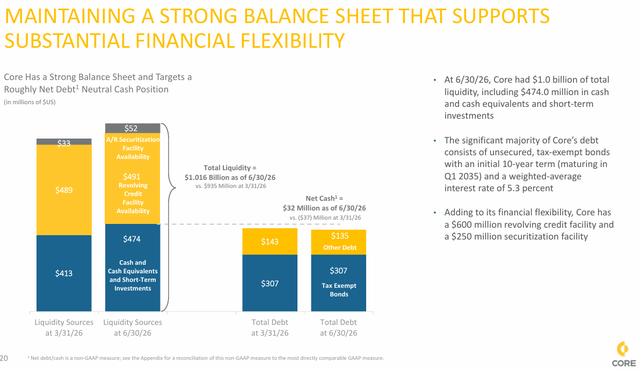
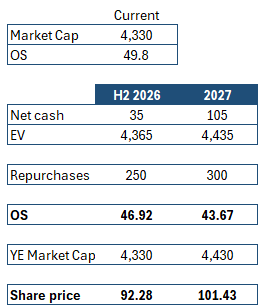
Encouraging sampling results at Core’s Powder River Basin operations suggest potential opportunities to use existing mining infrastructure and byproduct streams. That approach could reduce the need to develop an entirely separate mining operation. The initiative remains a longer-term opportunity. Commercial production, revenue growth and profitability would depend on successful testing and development. Financial Position and Valuation Core reported approximately $474 million in cash and $442 million in debt at the end of the second quarter. Second-quarter earnings of $2.51 per share included the insurance settlement, making them less representative of recurring operating performance. Tucker forecasts approximately $0.75 per share for the third quarter, while expressing caution about stronger earnings expectations for subsequent periods. Her valuation assumes approximately $400 million in normalized free cash flow in 2027 and substantial additional repurchases. She also projects approximately $250 million in repurchases during the second half of 2026. These are the author’s estimates.
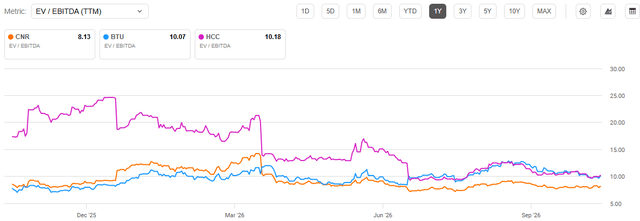
Tucker’s approximately $100-per-share valuation reflects the anticipated effect of repurchases and retained cash. She also considers Core attractively valued relative to peers, including Peabody Energy, and identifies options strategies as one possible way to establish exposure.
Risks and Outlook Coal prices remain the principal operating risk. Lower thermal coal prices could reduce cash generation, while weaker steel demand could pressure metallurgical coal markets. Tucker also identifies changes to the repurchase program as a risk to her investment thesis. Buybacks depend on available cash, operating conditions and management’s capital-allocation decisions. Her overall assessment remains favorable: Core’s operating assets, financial position and potential cash generation could support additional shareholder returns. The pace of those returns will depend on coal markets, operating performance and the company’s execution. |
|