|
Signature Sponsor
November 15, 2026 - Warrior Met Coal (HCC) is back in focus after reporting third quarter 2026 results that showed higher sales, revenue, and net income, along with reaffirmed full year coal production and sales guidance.
Despite a strong third quarter print and reaffirmed guidance, Warrior Met Coal’s share price has eased. The stock is down 7.33% over the past month and 15.49% over 90 days from the latest close of US$83.35, even as total shareholder return sits at 8.78% over one year and 347.93% over five years. This suggests that long-term momentum remains intact, while shorter-term sentiment appears more cautious.
Warrior Met Coal just posted stronger year-on-year earnings, yet the share price has pulled back sharply. Is this a value entry for the bulls or a warning sign that the bears have the better read on the stock’s worth?
Most Popular Narrative: 24% Undervalued
On the analyst consensus Narrative on Simply Wall St, Warrior Met Coal screens as undervalued, with a fair value of $109.33 versus the latest close at $83.35, which sets up a very cash flow driven thesis for the stock.
The ahead-of-schedule and on-budget launch of the Blue Creek longwall in early Q1 2026 accelerates Warrior Met Coal's transition from capital investment to higher-volume revenue generation. Q2 2026 record sales volumes of 3.7 million short tons and a 45% increase in production indicate further potential impact on revenue and net margins as low-cost volumes continue to ramp.
Result: Fair Value of $109.33 (UNDERVALUED)
Still, the Warrior Met Coal narrative could be tested if steel demand stays weak and if second tier coking coal prices and freight costs continue to pressure realized margins.
Another View: Cash Flows Point the Other Way
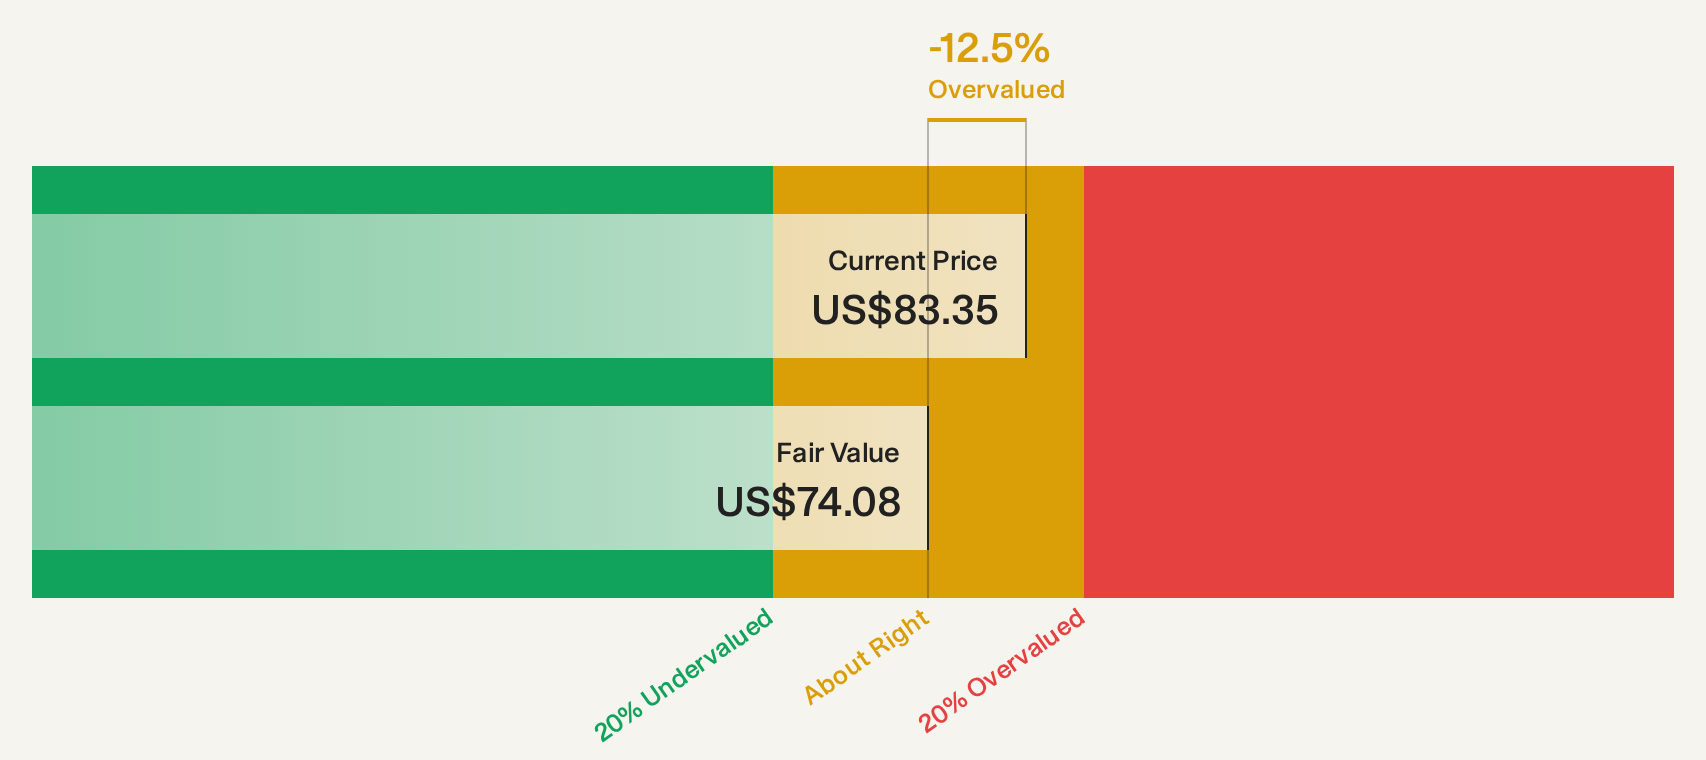
There is a catch. While analysts on Simply Wall St frame Warrior Met Coal as about 24% undervalued on earnings forecasts, the SWS DCF model flags the shares as expensive, with an estimated future cash flow value of US$74.08 versus the current US$83.35 price. That gap suggests less margin for error if the growth narrative stumbles.
|
|